Global business · 7 min read
VAT invoice requirements: what UK and EU businesses must include
A VAT invoice needs more than a standard one — a registration number, a tax point date, and rate breakdowns per line. Missing one field is a common reason invoices get sent back.
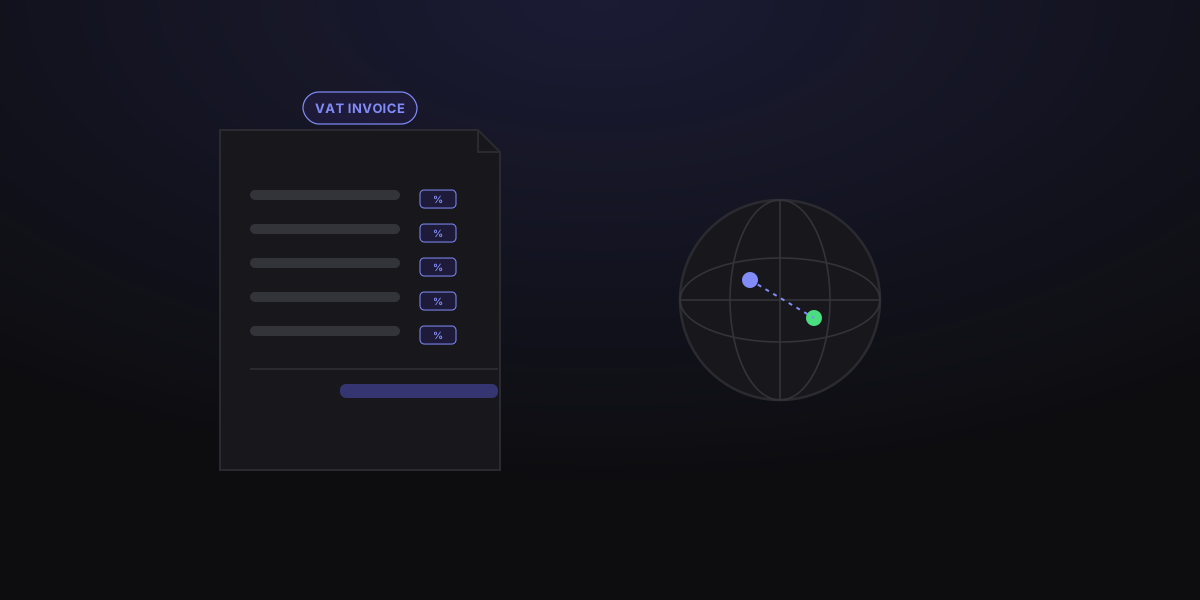
If your business is VAT-registered in the UK or the EU, an invoice isn't just a payment request — it's also a tax document that your client's accounting system and your own VAT return both rely on. That means a handful of fields are effectively mandatory, not optional formatting choices, and leaving one off is one of the more common reasons an invoice bounces back from a client's finance team.
This is general guidance, not tax advice specific to your situation — VAT rules vary by country and change periodically, so confirm anything that affects a filing with an accountant or your local tax authority.
Worked example
A UK agency invoicing an EU client
A UK-based design agency completes a branding project for a VAT-registered client in Ireland. Because this is a B2B cross-border service, the agency doesn't charge UK VAT — the Irish client accounts for it under the reverse charge.
- Net amount
- £4,000.00
- VAT charged
- £0.00 — reverse charge applies
- Invoice note
- "Reverse charge: VAT to be accounted for by the recipient"
- Client VAT number
- Included in full, verified format
Original diagram
VAT invoice decision tree
- 1Check if you're VAT-registered
- 2Determine if sale is B2B or B2C
- 3Apply correct VAT rate or reverse charge
- 4Include all mandatory fields per invoice type
Who actually needs to issue a VAT invoice
If you're registered for VAT — which becomes mandatory in the UK once taxable turnover crosses the current threshold, and follows similar registration thresholds across EU countries — you're generally required to issue a compliant VAT invoice for standard-rated, reduced-rated, and zero-rated sales to other VAT-registered businesses.
Even businesses below the mandatory threshold sometimes register voluntarily — often to reclaim VAT on their own purchases, or because larger clients expect to see a VAT number on incoming invoices. Once registered, the same invoicing rules apply.
The core fields a valid VAT invoice must include
A full VAT invoice needs considerably more detail than a standard commercial invoice. Missing any of these is the most common reason a client's accounts payable team sends an invoice back.
- A unique, sequential invoice number.
- The invoice date and the tax point date, if they differ.
- Your business name, address, and VAT registration number.
- The client's name and address, plus their VAT number for B2B sales.
- A clear description of the goods or services provided.
- The quantity and unit price, excluding VAT, for each line item.
- The VAT rate applied to each line — not just an overall rate.
- The VAT amount charged per rate, shown separately from the net total.
- The total amount excluding VAT, the total VAT charged, and the total including VAT.
Simplified VAT invoices vs. full VAT invoices
Not every sale requires the full field list above. For smaller retail-style transactions under a set value threshold, a simplified VAT invoice is often acceptable. It typically needs just your business details and VAT number, the date, a description of the goods or services, and the total including VAT at the applicable rate. Simplified invoices work well for point-of-sale receipts; anything B2B, higher-value, or cross-border should generally use the full format.
Reverse charge and cross-border notes
Selling to a VAT-registered business in another country introduces extra considerations. For many B2B cross-border services, the buyer accounts for VAT in their own country (reverse charge) — the invoice must state this explicitly. Goods exported outside the VAT area are often zero-rated rather than VAT-exempt. Since Brexit, UK-to-EU and EU-to-UK sales generally follow export and import rules rather than the old intra-EU VAT treatment.
Common VAT invoice mistakes
A few errors come up repeatedly in VAT invoicing.
- Leaving off your VAT registration number.
- Applying a single VAT rate to the whole invoice when line items fall under different rates.
- Forgetting the reverse-charge note on eligible B2B cross-border services.
- Confusing the invoice date with the tax point date when the two genuinely differ.
Common questions
Helpful clarifications
Do I need to charge VAT on invoices to clients in other countries?
It depends on whether the client is a business or a consumer, and which country they're in. Many B2B cross-border services fall under the reverse charge, meaning you don't charge VAT and the buyer accounts for it themselves. Consumer sales and goods often follow different rules, so check the specific case.
What is a tax point date and how is it different from the invoice date?
The tax point is the date that determines which VAT period a sale belongs to for reporting purposes — often the date goods are delivered or services completed, rather than the date the invoice is printed or sent. The two are frequently the same, but not always.
What's the difference between zero-rated and VAT-exempt?
Zero-rated sales are still technically taxable, just at a 0% rate, and you can usually still reclaim VAT on related costs. Exempt sales aren't taxable at all, and you generally can't reclaim related input VAT. They look similar on an invoice but are treated differently in your VAT return.
Can I issue a VAT invoice in a foreign currency?
Often yes, but many tax authorities still require the VAT amount to also be shown or convertible into your local currency using an approved exchange rate, for reporting purposes.
Is a VAT registration number always required on the invoice?
For a full VAT invoice, yes — your own VAT number is required, and the client's VAT number is required for B2B sales. Simplified invoices for smaller transactions have a shorter list of mandatory fields, but your own VAT number is still typically expected.
What happens if I forget to charge VAT when I should have?
You're generally still liable for the VAT that should have been charged, even if it wasn't itemized on the original invoice. The usual fix is issuing a corrected invoice or a supplementary one for the missing VAT amount.