Client billing · 7 min read
Rebilling expenses to clients: markups, mileage and disbursements
Costs you pass on to a client attract more scrutiny than your own fees, because the client can price-check them. Presenting them well is the difference between a quick approval and a line-by-line argument.
Nobody queries an hourly rate they already agreed. Everybody queries a 340 flight, because they can look up what that flight cost. Rebilled expenses are the most scrutinised part of most invoices, and they are also the part most people prepare least carefully.
Worked example
Worked example
A consultant delivers a two-day workshop at a client site in another city. The invoice reads:
- Professional fees
- Workshop design and delivery, 2 days at 1,400 → 2,800
- Expenses (at cost) Return flight, 14–16 Sept, workshop delivery
- 186
- Accommodation, 2 nights, 14–16 Sept
- 240
- Printed workbooks, 24 copies
- 96 (approved by email 9 Sept)
- Airport transfers, 4 journeys
- 52
Original diagram
Rebilling expenses to clients: markups, mileage and disbursements workflow
- 1Agree the rules before you spend anything
- 2At cost, or with a markup?
- 3Mileage and per-unit rates
- 4Costs paid on a client's behalf
Agree the rules before you spend anything
Almost every expense dispute traces back to something that was never agreed. Settle five things at the quote stage:
Two sentences in a quote cover most of this: "Travel and materials are billed at cost plus 10% handling. Individual items above 250 will be approved in advance."
- What is billable. Travel, accommodation, materials, software, subcontractors, courier, print — list the categories rather than leaving it open.
- What is included in your fee. Local travel, general software, your own equipment. Saying what is not billable prevents more arguments than saying what is.
- Whether anything is marked up, and by how much.
- Approval thresholds. "Costs above 250 need written approval first" protects both sides.
- Evidence expectations. Receipts above a threshold, attached to the invoice.
At cost, or with a markup?
Both are legitimate. The problem is only ever the undisclosed version.
Pass through at cost:
Cleanest for professional services where expenses are incidental — a train fare, a domain renewal. Easy to justify, no explaining required, and it signals that you are not making money on the client's spending.
Cost plus handling:
Appropriate where sourcing and managing the cost is genuinely part of the job: specifying materials, briefing and quality-checking a subcontractor, carrying the cash-flow risk of paying a supplier before the client pays you. Common percentages sit in the 10–20% range depending on trade and involvement.
If you mark up, say so on the invoice. A line reading "Materials (at cost plus 15% handling)" is transparent and rarely challenged. The same markup discovered by a client who recognises the supplier price reads as something hidden, even when it was agreed months earlier.
The alternative: build it into the fee:
For predictable, small expenses, folding them into your rate removes the entire administrative burden. Fewer lines, fewer receipts, fewer questions. This works badly for variable or large costs, where a client reasonably wants to see what they are paying for.
Mileage and per-unit rates
For recurring travel by vehicle, a stated per-distance rate is simpler than collecting fuel receipts. Show the journey and the distance on the line, not just a total. Many countries publish standard mileage rates that are commonly used as a benchmark, and the tax treatment differs by jurisdiction — confirm what applies to you and then apply one rate consistently across all clients.
Costs paid on a client's behalf
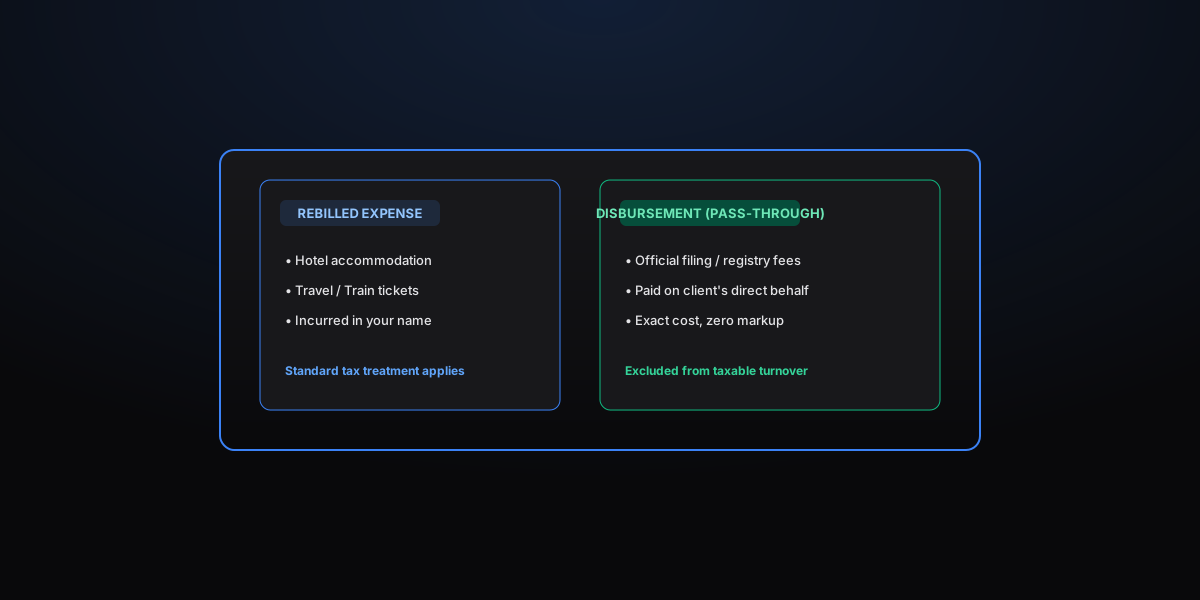
There is a meaningful distinction between a cost you incur to deliver your service and a cost you pay on the client's behalf, where they are really the third party's customer — a registration fee or statutory charge paid in their name, for example. In some jurisdictions these are treated differently for tax. If paying costs on behalf of clients is a regular part of your work, it is worth getting this confirmed once rather than guessing invoice by invoice.
Common questions
Helpful clarifications
Can I add a markup to expenses I bill back to a client?
You can, provided it was agreed in advance. A handling markup on materials or subcontracted work is normal in many trades, because sourcing and managing those costs is real work. What causes disputes is an unannounced markup discovered when a client recognises a supplier price. Agree the percentage at the quote stage and state on the invoice whether costs are at cost or include a handling charge.
Should I bill expenses on the same invoice as my fee?
Usually yes, but in a clearly separated section with its own subtotal. Mixing travel costs in among your professional fees makes the invoice harder to approve and invites line-by-line scrutiny of the whole document. A separate expenses block with a subtotal lets an approver check the part they care about quickly.
Do I need to attach receipts?
Attach them for anything above a threshold you agree with the client, and keep them all regardless. Many corporate clients will not approve rebilled costs without evidence, and receipts are also part of your own records. A single PDF of receipts appended to the invoice is easier for everyone than a separate email of photographs.
How should I bill mileage?
Use a stated per-distance rate agreed in advance, and show the journey and distance on the invoice line rather than a lump sum. Many countries publish standard mileage rates that are widely used as a reference point, and tax treatment of mileage varies, so confirm the position locally. Whatever rate you use, apply it consistently across clients.
What is the difference between an expense and a disbursement?
Broadly, an expense is a cost you incur in delivering your own service, such as travel to a client site. A disbursement is a cost you pay on the client's behalf, where they are really the customer of the third party, such as a registration fee paid in their name. The distinction can affect tax treatment in some jurisdictions, so if you regularly pay costs on behalf of clients it is worth confirming how each should be handled.